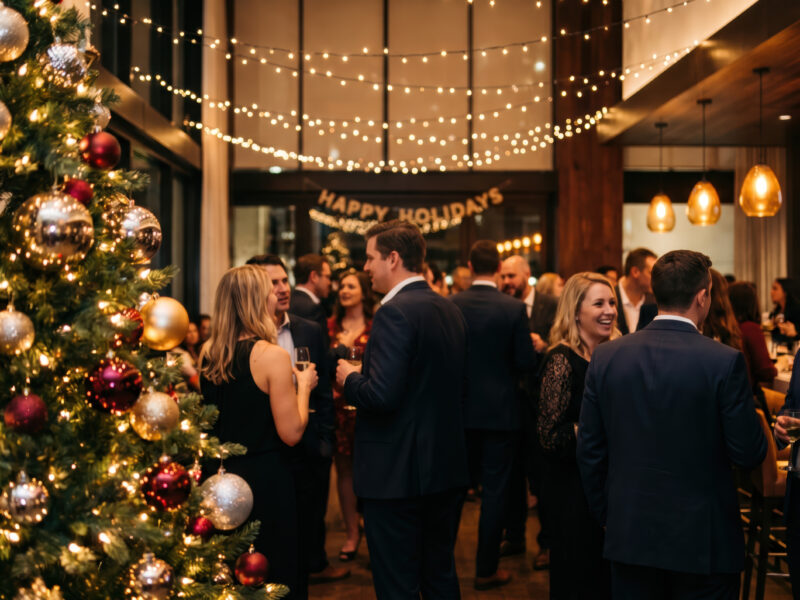
With Christmas fast approaching, many employers will be planning festive celebrations or providing employees with gifts, vouchers or other seasonal items.
What many employers do not realise is that these items can give rise to tax and National Insurance contribution liabilities (NIC) unless specific exemptions apply. If benefits are taxable and are not reported correctly, HMRC may seek to recover the unpaid tax and NIC, together with interest and penalties.
Where benefits are taxable the default position is often that the employer bears the NIC cost while employees pay the income tax through their tax code. This can result in an unexpected tax charge for employees and likely does not reflect the employer’s intention of providing a festive celebration or gift to staff. Employers can choose to meet the tax liability for staff entertaining/gifts provided to team members by getting a PAYE Settlement Agreement (PSA) in place with HMRC.
Exemptions available
Subject to meeting the relevant conditions, Christmas parties, meals and gifts may qualify for exemption from tax and NIC under either the:
- Annual functions exemption
- Trivial benefits exemption
The trivial benefits exemption may be available for certain gifts and vouchers, while the annual functions exemption can apply to Christmas parties and other staff events.
It is important to note that both exemptions operate on an all-or-nothing basis. Where the cost exceeds the relevant exemption limit, the entire benefit becomes taxable, not just the excess amount.
Employers should ensure they consider the full cost of providing the benefit when assessing whether an exemption applies.
For example:
- For staff events, this includes the VAT-inclusive cost of the event together with associated travel and accommodation costs.
- For gifts, this includes the VAT-inclusive cost of the gift, together with any delivery, packaging, wrapping and greeting card costs.
Determining whether an exemption applies is not always straightforward, particularly where multiple events are held during the year or Christmas gifts double up as a thank you for hard work in the year for instance. Communications to employees are important when considering the tax treatment. Obtaining employment tax advice can help ensure the correct treatment is applied and avoid unexpected liabilities arising from an HMRC review.
Reporting taxable benefits
Where an exemption is not available, many employers choose to settle the tax on behalf of employees through a PAYE Settlement Agreement (PSA).
A PSA allows an employer to pay the income tax and NIC due on qualifying benefits, ensuring employees do not suffer a personal tax charge.
If you do not currently have a PSA in place, there is still time to apply to HMRC for one covering the 2026/27 tax year.
How we can help
Our employment tax specialists can support you with:
- Reviewing Christmas parties, gifts and vouchers to determine whether an exemption applies.
- Identifying planning opportunities to minimise or remove tax and NIC liabilities where possible.
- Advising on the reporting requirements for taxable benefits, including items such as staff entertainment, team-building events, incentive awards, long-service awards and free or subsidised meals.
- Assessing whether a PSA would be beneficial for your business.
- Assisting with PSA applications and annual PSA calculations.
Need advice before the festive season?
Getting the tax treatment right before benefits are provided can help avoid unexpected costs and ensure employees receive the full value of your festive treats. If you would like to discuss your Christmas events, gifts or PSA requirements, please get in touch with our Employment Tax team.